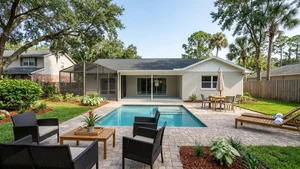
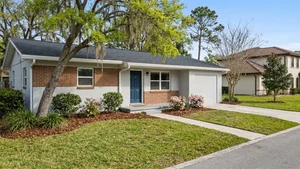
If you own a single-family house in Longwood, the citywide median sale price is the wrong number to value it by. Single-family homes held near $395,000 at the median and closed at nearly 98% of their list price.
Starting from the single-family price per square foot gives you a much better baseline. You can expect to give up roughly 2% at the closing table, so understanding the gap between your tax value, an online estimate, and real market data makes a difference in your bottom line.
Key Takeaway
The single-family median held nearly flat over the past year while the all-homes figure fell far more. Start with a price-per-square-foot estimate, then get a CMA before you list or a licensed appraisal if a lender or court needs the number.
Who This Guide Is For
You own a home in Longwood and want a realistic number for what it would sell for, before deciding whether to list, refinance, or question your Seminole County value.
What Is My Home Worth in Longwood, FL?
The citywide median sale price for all homes in Longwood sits at $349,833, a 12.3% drop over the last year. Look strictly at single-family homes, though, and the median price is $394,843 over the same 90-day period ending September 30, 2026. That single-family figure barely moved year over year.
The gap between those two numbers reflects which types of homes sold recently, not some broad collapse in house values. Out of 48 total sales in that 90-day window, 39 were single-family homes, leaving fewer than 10 sales spread across all other property types. An owner who anchors to the 12% headline drop risks underpricing a house that is holding its value just fine.
A 90-day citywide median still says nothing about your specific roof, lot size, or street. If you own a condo or townhouse, you should ask for a comparative market analysis (CMA) built on recent sales in your specific community, because there is no reliable 90-day median for your property type.
Longwood Home Values at a Glance
These approximate figures cover the 90 days ending September 30, 2026, and show the difference between single-family houses and the broader market.
Single-family median sale price: $394,843, down 1.3% year over year (90 days ending Sept. 30, 2026)
All homes median sale price: $349,833, down 12.3% year over year (90 days ending Sept. 30, 2026)
Median sale price per square foot: $239 single-family; $223 all homes (90 days ending Sept. 30, 2026)
Homes sold: 39 single-family; 48 all homes (90 days ending Sept. 30, 2026)
Median days on market: 35 single-family; 38 all homes (90 days ending Sept. 30, 2026)
Sale-to-list price: 97.8% single-family; 97.6% all homes (90 days ending Sept. 30, 2026)
Share sold above list price: 15.8% single-family; 14.9% all homes (90 days ending Sept. 30, 2026)
Months of supply: 3.7 single-family; 3.9 all homes (90 days ending Sept. 30, 2026)
Active inventory: 46 single-family; 61 all homes (90 days ending Sept. 30, 2026)
Condos and townhouses: no separate figures, because fewer than 10 of each sold in the window
How to Estimate Your Longwood Home's Value
A reliable valuation starts with comparable sales in your own subdivision from the last 90 days. You want homes within roughly 20% of your square footage and in similar condition. Pulling sales from the priciest streets in town won't help if your home sits in a different subdivision with different lot sizes.
Once you have those local comparisons, the citywide single-family median per square foot gives you a baseline to work from. Adjust that baseline against your own comparable sales rather than inventing dollar amounts for specific features. If you're deciding whether to list in the next few months, work through the math below, then look at the current market outlook for sellers.
Estimate for an 1,800-Square-Foot House
For an 1,800-square-foot single-family house, multiplying the square footage by the single-family median of $239 per square foot yields $430,200. That is already a sale-price estimate, because that figure comes from closed sales over the last 90 days ending September 30, 2026. Since single-family homes currently close at a median sale-to-list ratio of 97.8%, a seller hoping to net about $430,200 would need to list near $440,000.
From that $440,000 starting point, you adjust for what the median can't see. An older roof, a missing pool, a smaller lot, or dated interiors pull the number down; recent updates push it up. The per-square-foot figure comes from sold prices, so listing at your square footage times that rate means you're already aiming to sell at the market median.
There's another limitation worth knowing. A citywide median per square foot blends small and large homes together, and larger houses generally sell for less per square foot while smaller ones sell for more. This example is a starting point, not a finished price. Only same-size, same-subdivision comparable sales tighten the estimate into something you can list with confidence.
Appraisal vs. CMA vs. Online Estimate vs. County Value
Online estimates are free and instant, but they can't see your home's condition, upgrades, or specific lot features. A CMA from a listing agent is also free and offers much better accuracy. An agent builds a CMA on hand-picked local comparable sales and aims to find a realistic list price, though no lender will accept it for a loan.
A licensed appraisal costs money and takes time to schedule. It is the document a lender, court, or estate will accept. If someone else must approve the value of your property, you need a licensed Florida appraisal. You can verify any appraiser's license with the Florida Department of Business and Professional Regulation (DBPR) before hiring them.
The Seminole County just value is a different calculation entirely. It's set as of January 1 each year for tax purposes and doesn't represent a list price for your home. If your just value looks far off from what you think the house would sell for, you can compare your property tax and living costs to see how it affects your bottom line. For a real-world figure for selling, Todd Schroth's team can prepare a free CMA for a Longwood home.
What Affects Home Values in Longwood
Your subdivision and your specific street set the ceiling for your home's value, regardless of how many updates you make. Flood zones also affect pricing, and you can check your official flood zone on FEMA's Flood Map Service Center to review your safety and flood risk. Utilities matter to buyers too; you should confirm whether your home connects to city water and sewer or relies on a well and septic system. School boundaries influence demand, so you can check your specific zoning using the Seminole County Public Schools locator.
Beyond location, buyers price in the condition of your roof and your permit history. Citizens Property Insurance Corporation requires a 4-point inspection for properties over 20 years old and caps shingle roofs at 25 years before requiring extra documentation. An older roof can make a home harder to insure, so confirm your roof's age and permit history in county records before you set a price.
HOA costs are the other number buyers run. Ask your association for current dues and any pending special assessments. High monthly fees reduce a buyer's purchasing power, and that shows up in what they'll offer.
Longwood Housing Market Outlook for Sellers
Single-family homes in Longwood recently spent a median of 35 days on the market before going under contract. With 3.7 months of supply available, buyers have enough inventory to compare multiple properties, so your home's condition and its price relative to comparable sales will decide the outcome. Plan to carry the home for about five weeks before accepting an offer, plus the time it takes to close. Owners preparing for the market can review the steps for selling a home in Longwood.
Only 15.8% of single-family sales closed above their list price over the 90 days ending September 30, 2026. Pricing high in hopes of multiple offers is a bet on a minority outcome in this market. These figures give you a starting point, not an appraisal. You can request a CMA from Todd Schroth's team to get a specific value for your address.
Longwood Property Valuation FAQs
Which County Property Appraiser Values Homes in Longwood, FL?
The Seminole County Property Appraiser values homes in Longwood. Under Florida law, the appraiser must assess property at its market value, known as just value, as of January 1 each year. You can find your property's just value and taxable value by searching your address on the property appraiser's website.
Do Home Values Differ Between Longwood's ZIP Codes?
Yes, values differ across Longwood's ZIP codes and subdivisions. The citywide single-family median is a blend of all areas, so a specific neighborhood may average higher or lower. Ask an agent for a CMA filtered by your specific ZIP code and subdivision to get an accurate number.
How Much Does a Home Appraisal Cost in Longwood?
The cost depends on the property's size, acreage, and whether you need a rush order. Larger homes or complex lots typically raise the fee. Confirm the appraiser's license with the Florida DBPR before hiring them and ask for a direct quote.
How Long Is a Home Appraisal Good For?
It depends on the loan type. Under Fannie Mae guidelines, a conventional appraisal is valid for up to four months, though an update can extend it to 12 months. For FHA loans, the initial appraisal is valid for 180 days and can also be updated to reach one year from the original effective date.
Can I Challenge My Seminole County Property Value?
Yes. After Proposed Tax (TRIM) Notices are mailed in mid-August, you have 25 days to file a petition with the Value Adjustment Board. You can also request an informal review with the property appraiser before the deadline. This is not legal or tax advice.
Does My Save Our Homes Benefit Carry over If I Sell and Buy Again in Florida?
Yes, Florida law allows you to transfer your Save Our Homes benefit to a new homestead. You can port your accumulated assessment difference, up to $500,000, as long as you establish the new homestead within three tax years of abandoning the old one. Consult a professional for your specific situation, as this is not tax advice.